Personal or Business Bank Statements: Which One Actually Gets You Approved for a Mortgage in Florida?
Personal or Business Bank Statements: Which One Actually Gets You Approved for a Mortgage in Florida?
By Rayce Robinson, Owner & Lead Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
Once a self-employed homebuyer here in Seminole County discovers that bank statement loans exist, their next question is almost always the same:
“Should I use my personal account, my business account, or does it even matter?”
It is a fair question, and the honest answer is straightforward: it depends entirely on how your money actually moves through your business.
Traditional retail banks and credit unions evaluate self-employed borrowers through a rigid, one-size-fits-all lens. When your CPA rightfully uses legal tax write-offs to minimize your tax liability, the bank’s computer system sees low net taxable income and issues an automatic denial.
A Bank Statement Loan bypasses your tax returns completely. Instead of tax forms, wholesale lenders evaluate your actual monthly cash flow over a 12 to 24 month window.
Here is how personal versus business accounts compare, how underwriters treat them, and how to know which option will secure your highest approval amount.
*************************************************************************************
If Your Income Lands in Your Personal Account
This is the most common setup for sole proprietors, freelancers, independent real estate agents, and 1099 contractors who never opened a separate commercial business account.
How Underwriters Review Personal Statements:
Deposit Averaging: Lenders calculate your total eligible monthly deposits over 12 or 24 months to establish your gross qualifying baseline.
Direct Cash Flow: If you transfer funds from your business account into your personal checking as regular owner distributions, many wholesale lenders can count up to 100% of those net personal deposits as qualifying income.
Zero Paperwork Chasing: No corporate tax returns, no K-1s, and no complex year to date P&L statements. Underwriters review your cash flow directly from your statements.
The Bottom Line: If your personal account reflects consistent, steady monthly earnings without business operating expenses dragging it down, personal statements are often the fastest path to a clear approval.
*************************************************************************************
If You Run Operations Through a Business Account
For LLCs, S-Corporations, and partnerships with a dedicated commercial operating account, using business statements is often the cleaner approach.
How Underwriters Review Business Statements:
Separation of Funds: It keeps your company’s gross revenue clearly separated from your household expenses, which underwriters prefer for audit compliance.
Expense Ratios: Because top-line revenue is not pure take home pay, wholesale lenders apply an expense ratio (often defaulting around 50%, depending on your specific industry).
Maximizing Your Cash Flow: For low overhead service businesses (like consulting, marketing, or software), an independent broker can often submit a simple one page letter from your CPA or Enrolled Agent (EA). This documents a lower expense ratio, instantly boosting your qualifying income.
*************************************************************************************
What Happens If You Have Both?
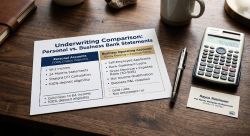
This is where many self-employed borrowers in Central Florida leave purchasing power on the table.
Depending on the wholesale lender, you can qualify using:
Business bank statements alone (factoring in the business expense ratio)
Personal bank statements alone (capturing 100% of your owner distributions)
A blended structure combining both accounts
Every wholesale lender evaluates this differently. They have different lookback periods, different requirements for business ownership percentage, and different comfort levels with money transferring between accounts.
This is the primary advantage of working with an independent wholesale mortgage broker instead of walking into a single retail branch. I shop across more than 100 competing wholesale lenders specifically because they don't all assess cash flow the same way. Finding the lender whose guidelines fit how your business actually operates can double your purchasing power.
*************************************************************************************
A Real World Central Florida Scenario
A local real estate agent in business here in Seminole County, with more than ten years in business, operated an LLC with an account showing healthy, consistent monthly deposits,
She ended up speaking with a local bank and after submitting documents and the necessary info, the loan officer turned her down flat. The tax returns showed lots of expenses, which are fairly normal when running a real estate company, but this made her taxable income appear too low for the home she wanted to purchase.
Same business. Same income. Same borrower.
She reached out and came to our office on South Central Avenue in Oviedo. We bypassed her tax returns completely and structured her file as a 12-month business bank statement loan with a wholesale lender specializing in bank statement mortgage programs.
This time after working with us to structure her loan, she was approved in days and able to get a home under contract and close in less than 30 days.
*************************************************************************************
What to Have Ready Before You Apply
You don't need a mountain of paperwork to get an upfront review. Here is what we look at:
12 to 24 Months of Bank Statements: Provide either personal or business statements. We will review both sets to determine which calculates the highest qualifying income.
CPA or Tax Preparer Letter: A brief letter verifying your business ownership percentage (must be at least 25% ownership).
Entity Verification: Your Florida business license, Articles of Organization, or Sunbiz listing confirming at least two years in business.
*************************************************************************************
Frequently Asked Questions (FAQ)
Can I combine personal and business bank statements?
In certain scenarios, yes. Some wholesale lenders allow a hybrid calculation if your transfers between entities follow a clear, documented pattern. Because wholesale guidelines vary significantly, shopping the wholesale marketplace is critical to find a lender that allows this structure.
If I have an LLC, am I required to use business statements?
No. Even if you operate an LLC or S-Corp, you can qualify using personal bank statements if you regularly transfer your business profits into your personal checking account as owner draws.
What if my personal and business finances are commingled?
Wholesale lenders have varying guidelines on commingled funds. Some lenders allow commingled accounts by applying a standard expense ratio, while others require separate accounts. We match your specific account history to the lender that accommodates your setup.
Which option provides a higher loan approval amount?
Neither account type is universally better. If you have a high-revenue business with low overhead, business statements paired with a CPA expense letter often produce the largest approval. If you take consistent personal draws, personal statements provide a direct, clean calculation. We review both to find the highest number.
Why Work with an Independent Wholesale Mortgage Broker?
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned and operated by Rayce Robinson in Oviedo, FL. The firm is completely independent, locally operated, and distinct from retail banks and credit unions.
Because we are completely independent, we are not tied to the rigid guidelines of a single retail bank. We shop your scenario across more than 100 wholesale lenders to find the lowest available rates, minimal closing fees, and underwriting guidelines that fit your actual income.
*************************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile: https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211
*************************************************************************************
Continue Learning
If you are Self Employed and researching loan programs, you will find this series helpful:
·Bank Statement Loans for Self-Employed Buyers in Central FL posted 9/1/2026
·Personal vs Business Bank Statements posted 9/3/2026
·Broker vs Bank or Credit Union posted 9/8/2026
·Expense Ratios / P&L Requirements posted 9/11/2026
·DSCR Loans Explained posted 9/16/2026