Bank Statement Loans for Self-Employed Buyers in Central FL
How to Get a Mortgage in Florida When You're Self-Employed (Without Using Your Tax Returns)
By Rayce Robinson, Owner & Lead Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
If you run your own business, you already know the punchline before the bank even says it out loud: your income is fine, your credit is fine, but your tax return doesn't "look" like enough. It's one of the most frustrating conversations I have with clients, and it's almost never about whether they can afford the home. It's about whether a spreadsheet built for W-2 employees knows how to read their kind of income.
There's a fix for this, and it's been around for years and it's just not something most banks bother explaining well.
Bank statement loans let self-employed borrowers qualify off 12 to 24 months of actual deposits instead of a tax return. No adjusted gross income line, no explaining away your write-offs. Just what came into your account.
*************************************************************************************
Why Your Tax Return Works Against You Here
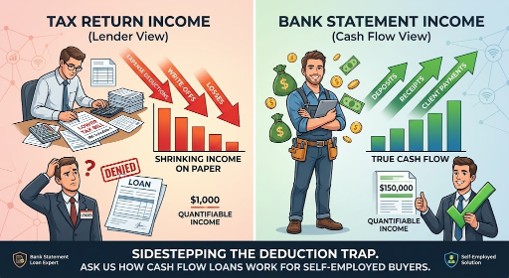
Your accountant's whole job is to lower what you owe the IRS. That's smart, and it's exactly what you should want. But the same deductions that shrink your tax bill also shrink the "income" a traditional lender sees on paper. So the better your books look to the IRS, the worse they can look to a bank, which is backwards, and it trips up good buyers constantly.
Bank statement programs sidestep that entirely by looking at cash flow instead of taxable income.
Who Tends to Do Well With This
I see this work best for 1099 contractors, small business owners a year or two into running things, and anyone whose deposits are strong but whose tax return doesn't reflect it. It's also the right conversation to have if a bank has already turned you down and pointed to your tax returns as the reason.
*************************************************************************************
Two Stories That Aren't Unusual at All
The business that was "too new" on paper
Over the years I have worked with so many clients who are newly self employed.Recently, another client of mine was just past the two-year mark running their cleaning business, early enough that most lenders get nervous, but with enough deposit history to prove it was real and growing. I knew already that a conventional lender would want more time on paper before they'd even look at it. We didn't need more time. The growing number of clients and deposits into her accounts showed the real story.This is the perfect type of scenario where a small business owner will automatically be denied by a big bank or traditional loan but alternative financing, such as a bank statement loan, creates options to qualify to buy a home.
Write-offs that can TANK a good file
Sometimes even established businesses can have issues.Another client I have worked with over the years had banked with the same institution for years and assumed that relationship would count for something. It didn't. Normal equipment write offs on their return tanked their taxable income, and underwriting couldn't get past it. We requalified them using 24 months of bank statements, and the numbers looked nothing like what the tax return showed, because they weren't the same thing.
Neither of these buyers had a weak business. They just walked into the wrong door first and needed someone to look at the bigger picture.
*************************************************************************************
What to Start Pulling Together if This Sounds Like You
12 to 24 months of bank statements, personal and/or business
A letter from your CPA confirming ownership and time in business
Basic business documentation such as license, Articles of Organization, whatever applies
We'll sort out together which lookback period and account type actually fits your situation. That's really the whole next conversation.
*************************************************************************************
Frequently Asked Questions:
How many months of bank statements do I actually need? Most programs work off either 12 or 24 months of statements, and which one fits you best depends on the lender and how consistent your deposits are. We'll match you to the shortest possible lookback that still tells a strong story.
Can I use personal bank statements, business statements, or both? Yes, depending on how your income flows through your accounts, lenders can look at personal statements, business statements, or a blend of both. (More on how to decide which fits you in the next post in this series.)
How long do I need to have been in business? Guidelines vary by lender, and most want to see around two years. That said, options exist for newer businesses with strong deposit history and compensating factors, like the client above who qualified just past the 2 year mark.
Will a bank statement loan cost more than a conventional loan? It's a different program built for a different kind of income documentation, so terms won't be identical to a conventional loan. The right move is running your actual numbers so you can compare real options side by side, not guess. As a broker we work with many different lenders and investors to always help you get the most competitive mortgage for your situation.
*************************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile: https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211
*************************************************************************************
Continue Learning
If you are Self Employed and researching loan programs, you will find this series helpful:
·Bank Statement Loans for Self-Employed Buyers in Central FL posted 9/1/2026
·Personal vs Business Bank Statements posted 9/3/2026
·Broker vs Bank or Credit Union posted 9/8/2026
·Expense Ratios / P&L Requirements posted 9/11/2026
·DSCR Loans Explained posted 9/16/2026