DSCR Loans: When the Property Qualifies You — Not Your Tax Returns
DSCR Loans: When the Property Qualifies You — Not Your Tax Returns
By Rayce Robinson, Owner & Senior Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
This one's a little different from the rest of this series. Bank statement loans still look at your income, just measured off your deposits instead of a tax return. DSCR loans skip your personal income altogether. No job history, no self-employment write-offs to explain, no personal debt-to-income calculation. The property itself is what qualifies you.
If you're self-employed and you're also buying or refinancing a rental property, this is often the more straightforward path of the two, worth knowing about even if you've already read the rest of this series.
*************************************************************************************************************************
What DSCR Actually Means
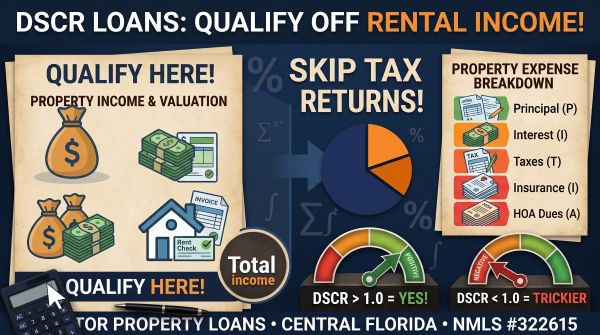
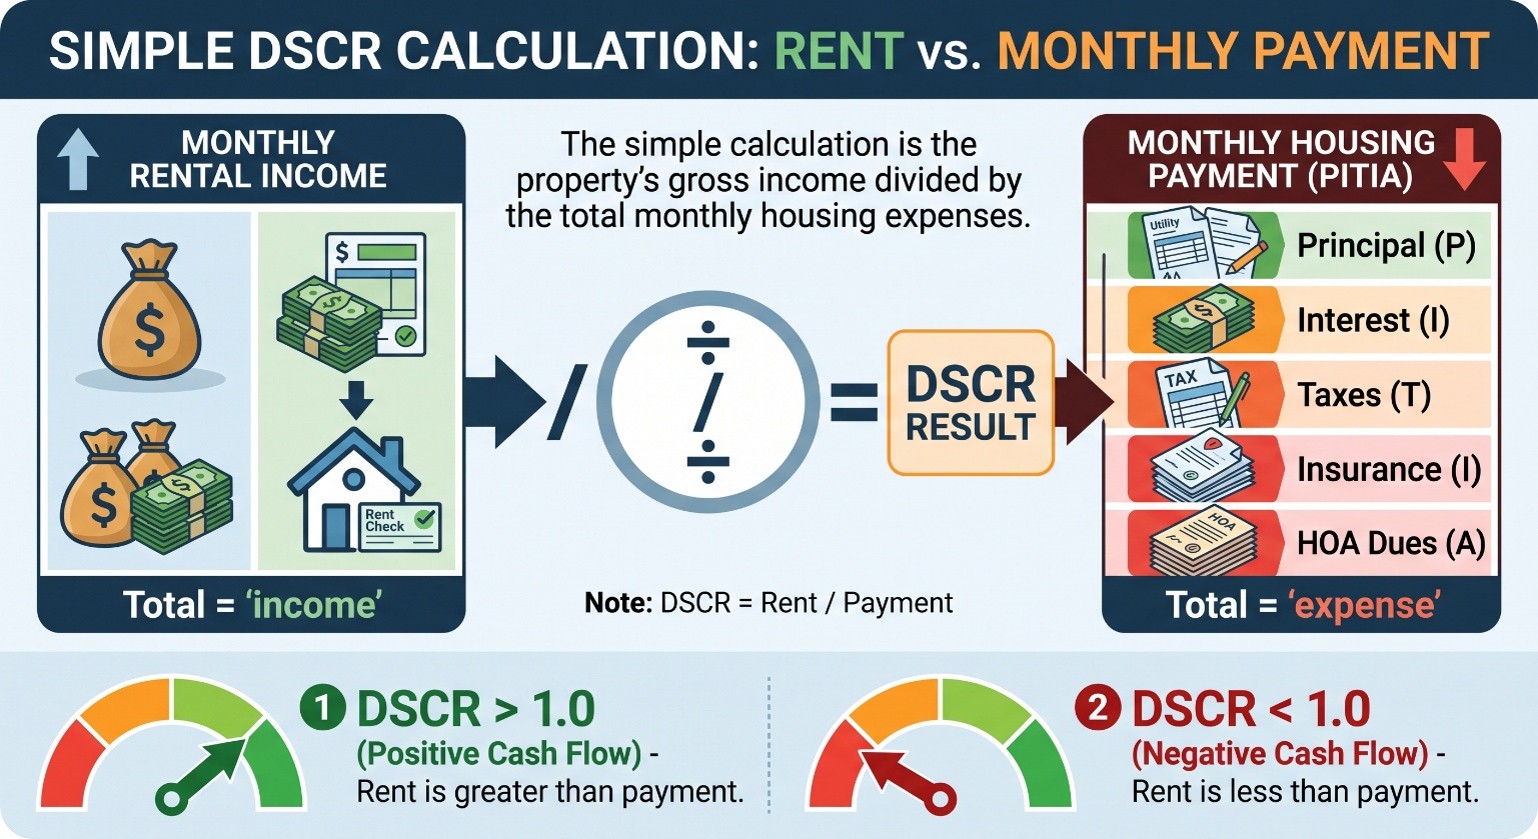
DSCR stands for debt service coverage ratio. It's a simple comparison: the property's monthly rental income divided by its monthly housing payment (principal, interest, taxes, insurance, and HOA dues where they apply).
A DSCR of 1.0 means the rent exactly covers the monthly payment. Above 1.0 means the property has a positive cash flow. Below 1.0 means the rent falls short of the full payment on paper, which doesn't automatically disqualify you, but it does change the conversation around down payment and pricing (interest rate).
*************************************************************************************************************************
Why Investors Like This
This loan is only for investment properties as the rental income is the driving force on how a buyer qualifies on this loan. No tax returns. No employment verification. No personal DTI (debt to income) ratio pulling your file in a direction that has nothing to do with the property itself. Whether you're buying your first rental or your tenth, the lender is underwriting the deal, not your resume, which is exactly why this program shows up so often for self employed investors whose personal income picture doesn't tell the full story.
*************************************************************************************************************************
Where the Ratio Comes Into Play
A DSCR at or above 1.0 is generally the easiest file to place, and it tends to come with more program options and better pricing. A ratio below 1.0 doesn't take you out of the running, plenty of lenders in the wholesale market will still work with it but it usually means a larger down payment or a stronger credit profile to offset the gap. This is exactly the kind of thing that varies a lot from lender to lender, which is where shopping the wholesale market instead of one bank matters.
*************************************************************************************************************************
How the Math Plays Out
Say a rental property brings in $2,750 a month, and the full monthly payment, principal, interest, taxes, insurance, and HOA — comes out to $2,500. That's a DSCR of 1.10: the rent covers the payment with some room to spare. Now say that same property's payment was closer to $3,200. The DSCR drops below 1.0, and the file starts to depend more on down payment and credit strength to make sense to a lender. Same property, same rent, a different conversation depending on how the numbers land.
*************************************************************************************************************************
A Cash-Out Refinance I Recently Closed
I recently closed a cash-out refinance for a client who'd built three units on a single parcel, his own project, ground up. He had financed some through the builder and used an equity line to fund the rest but ran into trouble when he went to the bank to try and get a loan to pay the builder and the line of credit. Through a traditional, income based route, he was having a tough time qualifying; his personal income just didn't support what he needed on paper. But those three units would bring in solid, consistent rent between them. Even though the properties weren't rented, we were able to have the appraiser provide us with what the market rents for each unit would be. We qualified him off the property's cash flow instead, and the rent pushed his qualifying number well above what the conventional route would have allowed. He closed the cash out refinance and pulled his equity back out of the property he'd built.
*************************************************************************************************************************
What to Have Ready
•A lease (for an existing tenant) or a rent schedule from the appraisal for a vacant or to be purchased property
•Funds for your down payment and reserves — no income documentation needed
•A recent credit report, credit strength plays a bigger role here than in a traditional owner-occupied loan
•Entity paperwork if you're closing in an LLC or similar structure
*************************************************************************************************************************
Frequently Asked Questions (FAQ)
Do I need to show any personal income at all? No, that's the core feature of a DSCR loan. Qualification is based on the property's rental income relative to its monthly payment, not your personal earnings.
What if my rental property doesn't quite cash flow? A DSCR below 1.0 doesn't automatically disqualify you. Options still exist, though a larger down payment or stronger credit typically comes into play, which lender fits depends on the specifics of your file.
Can I close in an LLC? In many cases, yes — this is common with DSCR loans and part of why investors tend to gravitate toward this program. We'll confirm it fits your specific setup and entity structure.
Is this only for experienced investors? Not necessarily. It's worth a conversation whether this is your first rental property or part of a larger portfolio, the property's numbers are what matter most.
I'm self-employed and investing, do I need a bank statement loan or a DSCR loan? It depends on what you're buying. DSCR fits an investment property being qualified on its own rental income; bank statement loans fit when your personal or business income is what's being evaluated, like on a primary residence. Some investors end up using both, just for different properties.
*************************************************************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile:https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211
*************************************************************************************************************************
Continue Learning
If you are Self Employed and researching loan programs, you will find this series helpful:
·Bank Statement Loans for Self-Employed Buyers in Central FL posted 9/1/2026
·Personal vs Business Bank Statements posted 9/3/2026
·Broker vs Bank or Credit Union posted 9/8/2026
·Expense Ratios / P&L Requirements posted 9/11/2026
·DSCR Loans Explained