Broker vs. Bank or Credit Union: Why Your Lender Choice Matters
Mortgage Broker vs. Bank or Credit Union: Why It Matters Far More When You're Self-Employed in Florida
By Rayce Robinson, Owner & Lead Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
For a salaried W-2 employee in Central Florida, the difference between using an independent mortgage broker and walking into a retail branch often feels subtle. The paycheck is steady, tax forms are predictable, and most traditional institutions process the paperwork through the same cookie cutter underwriting engine and systems.
For a self-employed business owner, trade contractor, or 1099 professional, that difference is night and day.
In fact, it is often the single deciding factor between holding the keys to a new home or walking away with a flat denial letter.
A retail bank or credit union can only offer you what they have built in house: their own narrow menu of loan products, governed by rigid internal underwriting overlays. When you walk into their lobby, their loan officers are bound to sell you only their proprietary options.
An independent wholesale mortgage broker operates completely differently. I am not an employee of a bank, and I am not bound to a single corporate product line. Instead, I take your financial picture and shop it directly across more than 100 competing wholesale lenders. My job is to find the exact lender whose guidelines are custom tailored to the way your business actually operates.
*************************************************************************************
Why the Broker Advantage Multiplies for Self-Employed Borrowers
Every self employed business in Seminole County handles cash flow differently.
A high-revenue roofing contractor in Winter Springs has different overhead than a software consultant working from home in Oviedo, or a real estate agent serving buyers across Geneva and Chuluota.
Because business profiles vary drastically, wholesale bank statement mortgage programs vary just as widely:
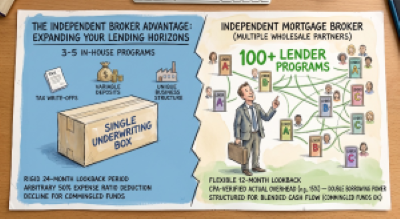
Lookback Periods: Some lenders require a rigid 24 months of bank statements, while our specialized wholesale partners often approve loans using only 12 months of deposits.
Expense Ratios: One lender might automatically deduct an arbitrary 50% operating expense factor, while another accepts a one-page CPA or Enrolled Agent (EA) letter showing your actual overhead is only 15%, instantly doubling your borrowing power.
Commingled Funds: Some institutions decline applications if personal and business funds touch the same account, whereas flexible wholesale programs are specifically structured to evaluate blended cash flow.
A retail bank has exactly one underwriting box. If your tax write offs or deposit patterns don't fit inside that single box, their system can trigger an automatic denial.
As an independent broker, if Lender A doesn't like your business structure, I already know that Lender B or Lender C was built specifically for your business model.
*************************************************************************************
What a "No" from a Retail Bank Actually Means
In over 20 years of originating mortgages across Central Florida, I have learned that a bank denial rarely means a self-employed borrower is financially unqualified.
More often than not, a "No" simply means:
The Bank's Software Only Understands W-2s: Most retail institutions rely entirely on automated Fannie Mae or Freddie Mac systems that read Line 31 of your Schedule C or your adjusted gross income on your 1040s. They simply do not offer true Non-QM bank statement alternatives.
Arbitrary Time-in-Business Rules: The bank might require three full years of entity filings, while our wholesale channels can clear files with 12 to 24 months of documented business activity.
Internal Underwriter Fear: If an underwriter sees regular transfers between business checking and personal savings, they issue a decline instead of taking the time to review the cash flow trail.
A denial does not mean you cannot buy a home. It simply means you knocked on the wrong door.
*************************************************************************************
A Real Scenario from Our Oviedo Office
Last year, the owner of an established service-based company in Seminole County visited our office at 235 South Central Avenue.
He had previously applied at his local retail banking institution. Despite having years of profitable business operations and consistently strong monthly deposits, the branch loan officer told him flatly that bank statement loans "simply were not something they did." He was offered zero alternatives, no guidance, and no path forward.
His tax returns showed significant vehicle depreciation and capital reinvestment, smart tax planning that made him look "unqualified" on paper.
Same entrepreneur. Same business. Same bank deposits.
We reviewed his last 12 months of business operating statements and submitted the file to a wholesale lender whose entire underwriting team specializes exclusively in self employed cash flow lending.
We documented his true operational cash flow, secured his approval within days, and closed on his home without touching his tax returns.
*************************************************************************************
Does Working with an Independent Broker Cost More?
No. In fact, it is frequently the opposite.
Many borrowers assume that because a broker shops the entire market, there must be an extra middleman fee layered on top. That is a myth.
Lower Overhead: Wholesale lenders do not carry the massive overhead of brick-and-mortar retail bank branch networks, multi million dollar TV ad campaigns, or bloated corporate hierarchies.
Wholesale Pricing Power: Because wholesale lenders compete aggressively for broker business every single day, their interest rate sheets and fee structures are often noticeably sharper than retail offerings.
Zero Affiliation Markups: When you work with Mid Florida Mortgage Professionals, you get transparent, wholesale pricing across 100+ lenders with lower rates and reduced closing costs.
*************************************************************************************
Frequently Asked Questions (FAQ)
What is the difference between an independent mortgage broker and a retail bank?
A retail bank or credit union only offers its own proprietary financial products. An independent mortgage broker like Rayce Robinson acts as your personal shopper across more than 100 competing wholesale lenders, matching your unique financial profile to the lender offering the lowest rates, lowest closing fees, and most flexible underwriting guidelines.
Can an independent broker help if my retail bank already turned me down?
Yes. A decline from a bank simply means you did not meet that specific institution’s internal guidelines. Wholesale lenders specialize in programs that retail banks do not offer—including 12- and 24 month bank statement loans, 1099 only qualifying, asset utilization, and DSCR investor financing.
Does working with a mortgage broker take longer than a bank?
No. Because independent brokers match your scenario with an underwriter who already understands self-employed cash flow, the process is typically faster. Retail banks often drag files out for weeks trying to force a non-traditional borrower into a traditional box before issuing a late decline.
Are independent mortgage brokers regulated and licensed?
Yes, under strict federal and state standards. Rayce Robinson is individually licensed (NMLS #322615), and Mid Florida Mortgage Professionals is a licensed corporate brokerage (Company NMLS #1587074) maintaining rigorous annual compliance, background checks, and continuing education.
The Independent Wholesale Broker Advantage
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned and operated by Rayce Robinson in Oviedo, FL. The firm is completely independent, locally owned, and distinct from retail banking institutions and credit unions.
Being independent is the reason I can shop your specific financial situation across more than a hundred wholesale lenders rather than trying to shoehorn your business into a single corporate box.
*************************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile: https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211
*************************************************************************************
Continue Learning
If you are Self Employed and researching loan programs, you will find this series helpful:
·Bank Statement Loans for Self-Employed Buyers in Central FL posted 9/1/2026
·Personal vs Business Bank Statements posted 9/3/2026
·Broker vs Bank or Credit Union posted 9/8/2026
·Expense Ratios / P&L Requirements posted 9/11/2026
·DSCR Loans Explained posted 9/16/2026