How to Shop Mortgage Rates Without the Stress (2026)
By Rayce Robinson, Owner & Lead Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
In the last post, Does Rate Shopping for a Mortgage Hurt Your Credit?I covered the big worry. Comparing lenders within a short window typically counts as one inquiry for scoring purposes. Knowing you can shop is half of it. The other half is comparing offers in a way that actually tells you which one is better.
******************************************************************************
Compare Loan Estimates, Not Advertised Rates
An advertised rate isn't an offer. It often assumes a large down payment, a high credit score, and discount points paid up front. Lenders can give you some kind of worksheet of if you actually apply, every lender will give you a standardized, three-page Loan Estimate. To make sure you are getting the best possible competitive numbers for your situation.
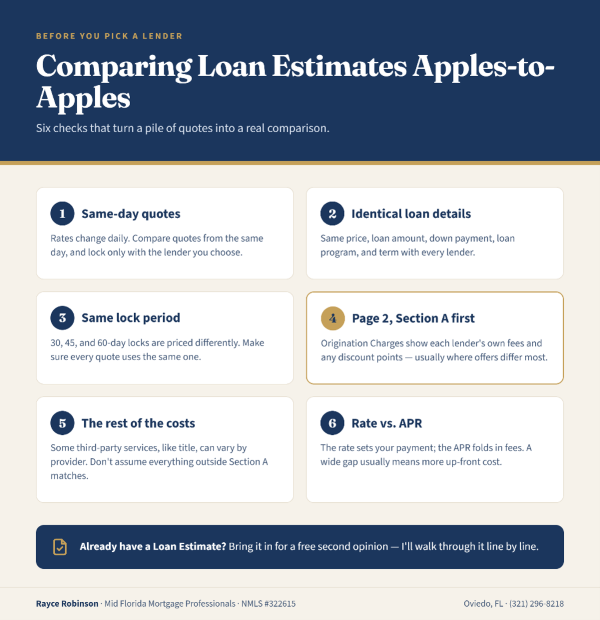
•Get quotes on the same day. Rates change daily, so quotes from different days don't line up. (You'll only lock with the lender you choose.)
•Use identical loan details. Same price, loan amount, down payment, loan program, and term with every lender.
•Match the lock period. A 30-day lock and a 60-day lock are priced differently.
•Start with Section A on page 2. "Origination Charges" is where each lender's own fees and any discount points show up, so it's usually where offers differ most.
•Then check the rest of the closing costs. Some third-party services, like title, can vary depending on the provider, so don't assume everything outside Section A is identical.
•Compare the APR with the interest rate. The rate drives your monthly payment; the APR folds in fees. A wide gap between the two usually means more upfront cost.
Points Aren't Automatically a Bad Deal
A lower rate that comes from paying discount points can make sense if you'll keep the loan long enough for the monthly savings to cover the up-front cost. It just shouldn't be a surprise. If one quote looks much lower than the others, check Section A before anything else.
******************************************************************************
Good News for 2026: The Phone Calls Have Mostly Stopped
If you've bought a home before, you may remember applying with one lender and then getting call after call from companies you'd never heard of. Those were trigger leads: the credit bureaus sold notice of your mortgage credit check to other lenders.
That changed on March 5, 2026, when the federal Homebuyers Privacy Protection Act took effect. Credit bureaus can now pass that information along only in limited cases, generally to a lender you already have a relationship with, like your current mortgage servicer or your own bank, or one you've given consent to. You may still hear from those, but the flood of cold calls from strangers is largely gone.
******************************************************************************
Where an Independent Broker Helps
Comparing lenders on your own means separate applications, separate document uploads, and separate conversations. As an independent broker, I compare pricing across more than 100 wholesale lenders on your behalf and lay out the best options side by side, same day, same loan details, so you're comparing real offers without doing all the legwork. (I wrote more about the difference in Broker vs. Bank or Credit Union.)
I also don't charge lender processing, underwriting, or administration fees, which keeps my own charges in Section A straightforward to read.
And it's still your decision. If you already have a Loan Estimate from another lender, bring it in. I'll go through it line by line and show you how it compares.
******************************************************************************
A Loan Estimate Worth a Second Look
As an independent broker, I get asked to review a lot of Loan Estimates. Some come from online lenders showing a very low rate, with fees and costs that look very low compared to what usually shows up at closing. Others come from local banks and lenders using a standard template that leaves the buyer with more questions than answers.
Last month, a local real estate agent referred a buyer to me who was struggling to figure out which lender actually made the most sense. We got on a Zoom call, and I laid out all the numbers side by side, with no marketing and no fluff.
For the first time, she could clearly see how her options compared and which one fit her situation.
Mortgage shopping can be tough, because there are a lot of ways to present the numbers that have little to do with what actually happens at closing. A clear, side by side comparison cuts through that.
******************************************************************************
Frequently Asked Questions
How many mortgage quotes should I get?
Comparing at least two or three is a good rule of thumb. What matters most is that the offers are directly comparable: same day, same loan details, same lock period. Working with a broker lets you compare many wholesale lenders through one application.
Why is the APR different from the interest rate?
The interest rate sets your monthly principal and interest payment. The APR includes certain up-front fees and points spread over the life of the loan, so it reflects the overall cost of borrowing.
Will I still get calls from other lenders after I apply?
Far fewer than before. Since March 5, 2026, federal law restricts credit bureaus from selling your mortgage inquiry to lenders you don't already have a relationship with or haven't consented to.
Does using a mortgage broker cost more than going to a bank?
Not necessarily, and often it costs less. Wholesale lenders compete for broker business and don't carry retail branch overhead, and I can often save on lender junk fees such as underwriting, or administration fees.
******************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
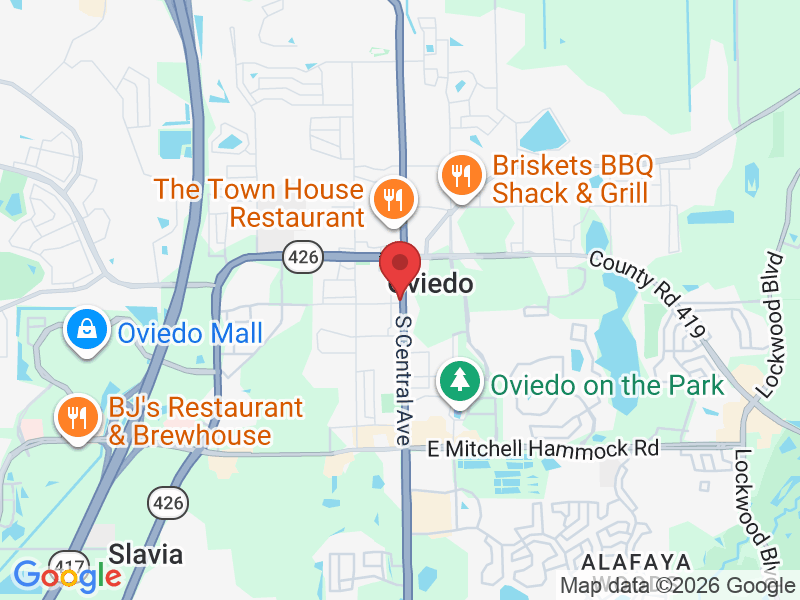
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile: https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211
******************************************************************************
Missed the first post? Start with: Does Rate Shopping for a Mortgage Hurt Your Credit?