Does Rate Shopping for a Mortgage Hurt Your Credit?
By Rayce Robinson, Owner & Lead Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
Does Rate Shopping for a Mortgage Hurt Your Credit?
I've been helping families finance homes since 2003, and one worry comes up almost every week. A buyer gets a quote from the first bank they talk to and takes it, even when they suspect they could do better, because they're afraid another credit check will lower their score.
The worry makes sense. It's usually misplaced, though, and it can end up costing more than the credit check ever would.
Short answer: comparing mortgage lenders or brokers within a short window typically counts as a single credit inquiry for scoring purposes, however many lenders check your credit. Credit scoring models were built this way on purpose, they know you're buying one home, not five.
******************************************************************************
How the Rate-Shopping Window Works
When a lender pulls your credit for a mortgage application or preapproval, it's a hard inquiry. On its own, one hard inquiry usually lowers a score by only a few points, and only temporarily.
Mortgage inquiries get special treatment. When several happen close together, scoring models count them as one. How close depends on the model:
•Newer FICO versions: a 45-day window.
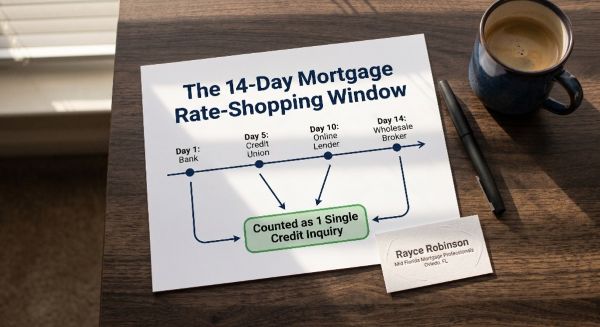
•Older FICO versions, including some of the Classic FICO scores used in mortgage lending: a 14-day window. (These numbers are subject to change and are set by the credit bureaus)
•VantageScore, which lenders approved by Fannie Mae and Freddie Mac can now use as an option: a 14-day window.
FICO also ignores mortgage inquiries from the most recent 30 days, so shopping that's underway doesn't count against you while it's happening. Each inquiry still appears on your credit report, it's the score calculation that treats them as one.(These numbers are subject to change and are set by the credit bureaus)
******************************************************************************
Why I Tell Clients to Think "Two Weeks"
You usually won't know which scoring model a lender uses, and in 2026 that's harder to predict than ever. As of September 9, every lender approved by Fannie Mae and Freddie Mac in some cases can use VantageScore 4.0 on eligible loans, alongside the Classic FICO scores the industry has relied on for decades.
So my rule is simple: do your serious rate comparisons within about 14 days. That window works under all of these models.
******************************************************************************
What Actually Hurts Your Score During the Loan Process
In my experience, comparing lenders is rarely what causes trouble. The problems usually come from other credit activity while the loan is in progress:
•Opening a store credit card to save on furniture or appliances for the new house
•Financing or leasing a car before closing
•Carrying higher balances on existing cards to cover moving costs
•Missing a payment in the middle of packing and moving
Mortgage inquiries are grouped together. Credit card and auto applications aren't, and new debt can change your debt-to-income ratio right when an underwriter is reviewing your file. My advice: hold off on new credit until after closing or at a minimum, make sure you talk to the loan officer you're going to work with about any of these changes in advance.
******************************************************************************
A Situation I Ran Into Recently
I get asked about credit pulls constantly, and I understand why. Some loan officers even tell clients not to let anyone else pull their credit once they have. Too often, that advice is really about keeping the client from shopping, not about protecting their score.
I recently worked with a young woman who was set on getting her mortgage through her bank. When things started going sideways there, she reached out to me with questions.
She was nervous about letting me pull her credit, and I didn't push. I explained how the rate shopping window works, and she did her own research too. Once she was comfortable, she gave me the go-ahead.
I was able to get her a preapproval much more in line with what she was actually trying to accomplish.
That's how your credit is designed to be used — to compare real options, not to lock you in with the first.
******************************************************************************
Frequently Asked Questions
How many mortgage lenders can I compare without hurting my credit?
There's no set limit. Mortgage inquiries within the shopping window are typically counted as one for scoring, whether two lenders check your credit or five.
Does getting prequalified hurt my credit?
Many prequalifications use a soft credit check, which doesn't affect your score. A full preapproval usually involves a hard inquiry, and that's the kind the shopping window covers.
How long does a mortgage inquiry affect my score?
A hard inquiry can stay on your credit report for up to two years, but scoring models generally only factor it in during the first year, and the effect is usually small.
Does checking my own credit lower my score?
No. Checking your own credit is a soft inquiry and has no effect on your score.
******************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
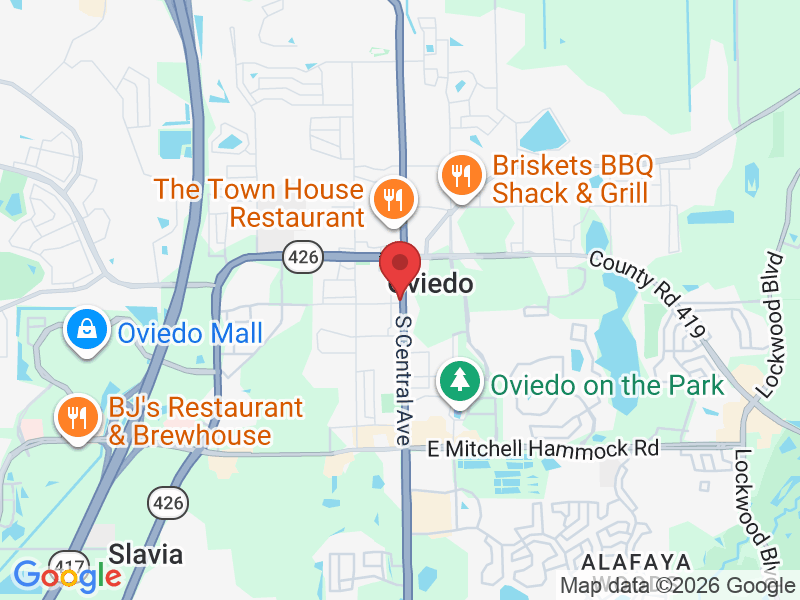
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile:https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211
******************************************************************************
Continue Learning
Next up: how to shop mortgage rates the smart way — comparing Loan Estimates, and why the phone calls have mostly stopped.