What Should Florida Homebuyers Look for in a Mortgage Professional?
By Rayce Robinson, Owner & Lead Mortgage Broker, Mid Florida Mortgage Professionals (NMLS #322615)
What Should Florida Homebuyers Look for in a Mortgage Professional and Real Estate Agent?
Buying a home in Florida involves more than finding the right property and getting a mortgage. The people helping you through the process matter, too. A recent Florida Realtors article highlighted real estate educator Paul Fedynich's discussion of mentorship making an important point: strong communication, relationship-building, preparation, and good professional habits can have a direct impact on the consumer experience.
For Florida homebuyers, that lesson applies to the entire homebuying team, including your real estate agent and mortgage professional. Whether you're buying your first home in Central Florida, moving to the Orlando area, or purchasing an investment property, you want professionals who can explain complicated decisions clearly, communicate consistently, and help you understand what happens next.
That is especially important when mortgage terms, loan requirements, closing costs, and monthly payments are involved.
******************************************************************************
Why Communication Matters When You're Buying a Home
A mortgage is a long-term financial commitment. The Consumer Financial Protection Bureau explains that a mortgage allows you to borrow money to purchase a home while giving the lender an interest in the property until the loan is repaid.
That sounds straightforward. The process itself can be anything but.
Homebuyers may hear terms such as:
Pre-approval
Interest rate
Annual Percentage Rate (APR)
Down payment
Closing costs
Escrow
Mortgage insurance
Loan Estimate
Closing Disclosure
A good mortgage professional should not simply give you a number and expect you to understand it. They should explain what the number means and how it fits into your overall homebuying budget.
This is one reason communication and relationships matter so much.
Florida Realtors' coverage of Paul Fedynich's comments focuses on how professionals can move beyond memorized scripts and technology to have genuine conversations with clients. Fedynich also emphasized that technology such as artificial intelligence and customer relationship management systems cannot replace the human work required to build trust.
For a homebuyer, that distinction can be valuable.
******************************************************************************
What Does Mortgage Pre-Approval Really Mean?
One of the first conversations you may have with a mortgage professional is about pre-approval.
A mortgage pre-approval is an indication that a lender is tentatively willing to lend you up to a certain amount, based on information and documentation reviewed during the process. It is not a guarantee that your final loan will be approved.
For example, imagine you're considering homes between $350,000 and $425,000 in Central Florida.
A pre-approval can help establish a realistic starting point for your search. It can also help your real estate agent understand the price range you're considering and demonstrate to a seller that you have taken steps toward securing financing.
But there is an important distinction:
What you qualify for isn't necessarily what you should spend.
Your lender evaluates factors such as income, assets, debts, and credit. Your personal budget also needs to account for expenses and priorities that may not be fully captured by a lender's maximum approval amount.
That is where an honest conversation can be more useful than simply looking at a maximum loan amount.
******************************************************************************
Pre-Qualification vs. Pre-Approval: What's the Difference?
These terms are sometimes used differently by different lenders.
In general, a pre-qualification may rely more heavily on information you provide, while a pre-approval can involve a more detailed review of your financial information. The CFPB notes that lenders use these terms differently, so homebuyers should ask exactly what a particular lender has reviewed before relying on the letter.
When comparing mortgage professionals, ask:
What information did you verify?
Did you review my income and assets?
Did you review my credit?
What could potentially change my approval?
How long is the pre-approval valid?
What assumptions were used?
These questions can help you understand where you actually stand before you start making offers.
******************************************************************************
Why Mortgage Communication Can Make the Homebuying Process Easier
The mortgage process involves a lot of moving parts.
For example, after you apply, you'll receive a Loan Estimate that provides important information about the loan, including estimated costs and payment information. Later in the process, you'll receive a Closing Disclosure with the final terms and costs. Federal rules generally require the Closing Disclosure at least three business days before closing.
These documents are designed to help consumers understand their loans, but they can still feel overwhelming.
A mortgage professional can help explain questions such as:
Why did my estimated payment change?
What is included in my monthly payment?
How much cash will I need at closing?
What are lender fees?
What is escrow?
What is mortgage insurance?
Should I consider paying discount points?
What is the difference between the interest rate and APR?
For example, your principal and interest payment may not represent your entire monthly housing expense. Property taxes, homeowners insurance, and mortgage insurance, when applicable, can increase the total payment.
Clear communication helps you see the bigger financial picture.
******************************************************************************
What Are Closing Costs?
Closing costs are expenses associated with getting the mortgage and completing the real estate transaction.
They can include items such as:
Lender or origination charges
Appraisal fees
Title-related costs
Government fees
Prepaid interest
Property tax and insurance deposits
Other required services
The exact costs vary by transaction, loan type, property, and other factors. The CFPB recommends reviewing the Loan Estimate and comparing the costs associated with different mortgage offers.
For Florida buyers, understanding these expenses early can make it easier to determine how much cash you actually need, not simply what home price you can technically qualify for.
******************************************************************************
Your Real Estate Agent and Mortgage Professional Are Part of the Same Team
The Florida Realtors article makes another useful point: professional success isn't simply about completing more tasks. Fedynich encourages agents to evaluate how they spend their time, delegate tasks that don't require their license, and develop relationships and communication skills.
From a buyer's perspective, the practical takeaway is simple: you want your professionals focused on helping you make informed decisions.
That might mean your real estate agent helps you evaluate properties, neighborhoods, contracts, and market considerations while your mortgage professional focuses on financing, qualification, loan options, documentation, and closing.
When those professionals communicate with each other, and with you the process can be easier to navigate.
Why Local Florida Mortgage Experience Can Matter
Florida isn't one single housing market.
Someone buying a home in Oviedo, Winter Park, Sanford, Lake Mary, Orlando, or another Central Florida community may have different questions depending on the property, financing situation, insurance considerations, taxes, HOA requirements, and loan program.
That's why local experience can be useful.
Mid Florida Mortgage Professionals focuses on helping Florida buyers understand their financing options and navigate the mortgage process. Rayce Robinson has more than 20 years of mortgage experience and has helped thousands of clients with mortgage financing in Florida.
The firm's approach emphasizes explaining loan options, guiding borrowers through documentation and underwriting, and maintaining communication through closing.
******************************************************************************
Frequently Asked Questions About Florida Mortgages
Should I get pre-approved before looking at homes?
Generally, getting pre-approved before seriously shopping can help you understand your potential price range and demonstrate financing readiness to sellers. However, a pre-approval is not a guarantee of final loan approval.
How much should I spend on a home?
Your lender can tell you how much you may qualify to borrow, but you should determine what monthly payment fits comfortably within your own budget. The CFPB specifically recommends considering your broader financial circumstances rather than focusing only on the maximum amount you qualify for.
What documents are needed for a mortgage?
Depending on your situation, lenders may request items such as pay stubs, W-2s, bank statements, tax returns, information about debts, and documentation of other income or assets.
What are closing costs?
Closing costs are the expenses associated with obtaining the mortgage and completing the home purchase. They can include lender charges, appraisal costs, title-related fees, government fees, prepaid expenses, and other transaction costs.
Why is communication so important during a mortgage?
It is important because mortgage transactions involve documentation, deadlines, underwriting, financial calculations, and changing circumstances. A professional who explains what is happening and what you need to do next can make the process easier to understand.
******************************************************************************
About Rayce Robinson & Mid Florida Mortgage Professionals
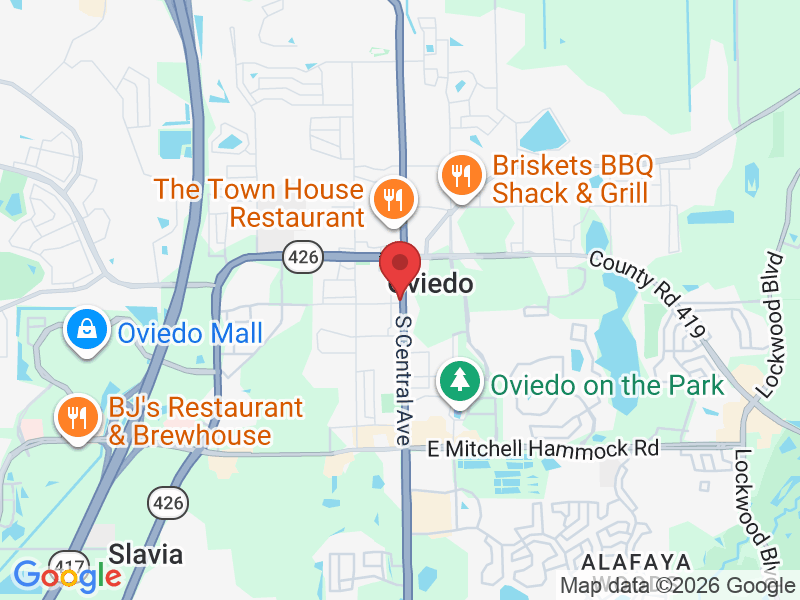
Rayce Robinson is the Owner and Lead Mortgage Broker at Mid Florida Mortgage Professionals | 235 S Central Ave, Oviedo, FL 32765 Click to open side panel for more information (NMLS #322615 / Corporate NMLS #1587074).
With over 20 years of local mortgage experience in Central Florida, Rayce specializes in helping homebuyers and owners across Oviedo (32765), Winter Springs, Chuluota, Geneva, and Seminole County secure low closing costs and competitive wholesale rates.
Mid Florida Mortgage Professionals is an independent wholesale mortgage brokerage owned by Rayce Robinson—completely independent and distinct from retail credit unions. As an independent broker, Rayce shops over 100 competing wholesale lenders on your behalf for Conventional, FHA, VA, Florida Hometown Heroes, DSCR, and Bank Statement loans.
Office Address: 235 S Central Ave, Oviedo, FL 32765
Google Business Profile: https://g.page/r/CfraNuIe8HMxEBM
Schedule a Call with Rayce Robinson: 321-377-4211