| 2-1 Buydown
What Is a 2-1 Buydown?
A 2-1 buydown is a temporary interest rate reduction designed to make homeownership more affordable during the first two years of the loan.
With a 2-1 buydown:
Year 1: Your interest rate is reduced by 2%
Year 2: Your interest rate is reduced by 1%
Year 3 and beyond: The loan returns to the full note rate for the remainder of the term
The reduced payments in years one and two are made possible by a temporary buydown fund, typically paid for by the seller, builder, or sometimes the buyer as part of closing costs.
KEEP IN MIND, DUE TO ROUNDING, THE NUMBERS MAY BE SLIGHTLY OFF. THIS IS NOT A GUARANTEED RATE OR COST BUT SHOULD GIVE A GENERAL IDEA OF THE NUMBERS. THIS IS NOT A COMMITMENT TO LEND NOR A PREAPPROVAL. FOR A CURRENT REAL LIFE QUOTE, PLEASE GIVE US A CALL (321) 377-4211
Curious about rates?
Disclaimer: The mortgage interest rates shown are for informational purposes only and are subject to change without notice. Actual rates and terms may vary based on individual credit profile, loan amount, property type, occupancy, loan-to-value (LTV), and other factors. Not all applicants will qualify for the lowest rates. Rates displayed may be provided by third-party sources and may not reflect current market conditions or all available loan programs. Please contact us directly for a personalized rate quote and to confirm current pricing and eligibility.
How a 2-1 Buydown Works
Instead of permanently lowering your interest rate, a 2-1 buydown provides short-term payment relief at the beginning of your loan—when budgets are often tight due to moving costs, furnishing a home, or adjusting to a new mortgage.
The funds used for the buydown are placed into an escrow account at closing and are applied automatically to reduce your monthly payment during the first two years.
Important: This is not an adjustable-rate mortgage. The underlying loan is typically a fixed-rate loan—only the payment is temporarily reduced.
Why Buyers Use a 2-1 Buydown
A 2-1 buydown can be a smart strategy if you:
Expect income growth in the next 1–2 years
Want lower initial payments while adjusting to homeownership
Are buying in a market where seller concessions are available
Plan to refinance if rates improve in the future
Key Details to Know
Available on many conventional, FHA, and VA loans
Requires seller, builder, or buyer-paid funds at closing
Payments automatically adjust—no action required from the borrower
If you refinance or sell during the buydown period, unused funds are typically applied to your loan payoff
Pros of a 2-1 Buydown
Lower monthly payments in the first two years
Helps buyers qualify more comfortably
Can make offers more competitive when sellers contribute
Provides breathing room during the early stages of the loan
Useful bridge strategy while waiting for future refinancing opportunities
Cons of a 2-1 Buydown
Payments increase after year two
Not ideal if your income is unlikely to grow
Requires upfront funds (often from seller concessions)
Not a long-term rate reduction
Is a 2-1 Buydown Right for You?
A 2-1 buydown works best when paired with a clear plan—whether that’s future income growth, expected refinancing, or seller-paid concessions.
Used strategically, it can significantly reduce early financial pressure without locking you into an adjustable loan or risky structure.
See if a temporary buydown is the right option for you. Connect with us today to learn more.
MID FLORIDA MORTGAGE BLOG
Broker vs. Bank or Credit Union: Why Your Lender Choice Matters
Compare mortgage brokers, banks, and credit unions to understand your lending options and choose the right mortgage lender for your home financing needs. ...more
Bank Statement Loans ,Self-Employed Loans &Mortgage Education
September 08, 2026•7 min read
Personal or Business Bank Statements: Which One Actually Gets You Approved for a Mortgage in Florida?
Personal vs. business bank statements can affect mortgage approval. Learn what lenders look for and how bank statements may impact your loan options. ...more
Bank Statement Loans ,Self-Employed Loans Loan Programs Mortgage Education &Mid Florida Mortgage Professionals
September 03, 2026•7 min read
Bank Statement Loans for Self-Employed Buyers in Central FL
Self-employed and your tax returns don't reflect your real income? See how bank statement loans let Florida buyers qualify off deposits, not tax returns. ...more
Bank Statement Loans ,Self-Employed Loans Loan Programs Mortgage Education &Mid Florida Mortgage Professionals
September 01, 2026•5 min read
Florida Hometown Heroes Underwriting Red Flags: Processing Errors and Repayment Realities
Learn the biggest Florida Hometown Heroes underwriting red flags, avoid costly processing delays, and improve your chances of closing on time. ...more
First Time Home Buyer ,Local Economy & Lifestyle Florida HomeTown People Loan Programs Home Buyer Tips Florida Market Insights Mid Florida Mortgage Professionals &Hometown Heroes Florida
August 05, 2026•4 min read
Do You Have to Pay Back Florida Hometown Heroes?
Learn when Florida Hometown Heroes funds must be repaid, the four repayment triggers, and how the 0% deferred second mortgage affects your equity. ...more
Florida Real Estate Market ,First Time Home Buyer Refinancing Education Florida HomeTown People Investment Property Loans Loan Programs Florida Market Insights Mid Florida Mortgage Professionals &Hometown Heroes Florida
August 03, 2026•4 min read

How to Apply for Florida Hometown Heroes
Learn how to apply for Florida Hometown Heroes with our step-by-step guide, from pre-approval to reserving your state down payment assistance funds. ...more
Florida Real Estate Market ,First Time Home Buyer Florida HomeTown People Loan Programs Home Buyer Tips Florida Market Insights Mid Florida Mortgage Professionals &Hometown Heroes Florida
July 31, 2026•4 min read

WHAT OUR CLIENTS SAY
Our clients are at the center of everything we do. Their experiences reflect our dedication to clear guidance, trusted mortgage expertise, and a home-financing experience built around care and understanding.
Contact Info
We’re here to make your home financing experience smooth and stress-free. Contact our team anytime — we’re ready to guide you through every step of your homebuying journey.

Location
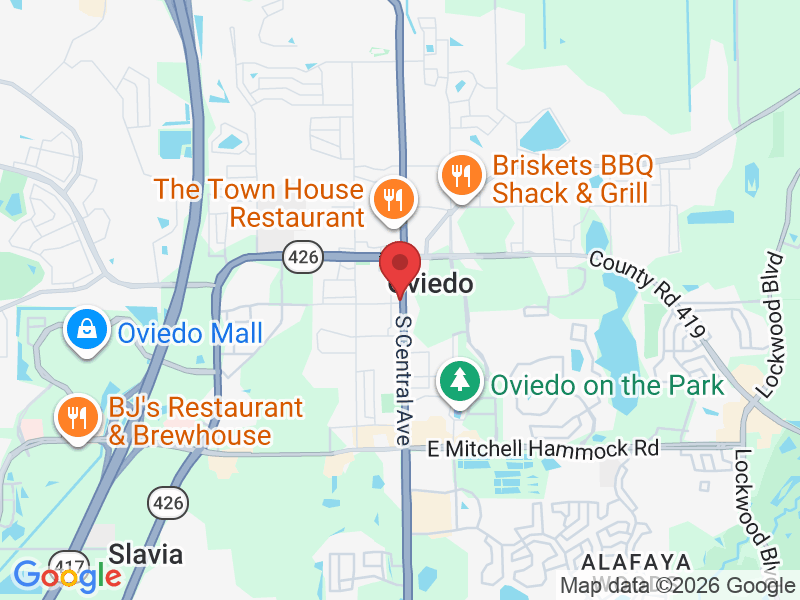
235 S Central Ave, Oviedo Florida 32765


Phone


Mid Florida Mortgage Professionals
Company NMLS# 1587074
Rayce Robinson
LO NMLS # 322615
235 South Central Ave
Oviedo, Florida 32765
© 2026 Mid Florida Mortgage Professionals. All rights reserved. Mid Florida Mortgage Professionals is not affiliated with any government agencies. This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Equal Housing Opportunity. NMLS Consumer Access